For IRA owners
Your IRA beneficiary designation: is it set up the way you want?
The beneficiary form, not your will, decides who gets your IRA.
The short answer
The form you filed with your IRA company decides who inherits your IRA and which rules they follow. Naming an estate, a charity or the wrong kind of trust next to people can shorten everyone's payout.
Reviewed November 2026 against IRS rules. Written by Onesta from IRS sources.
"My will takes care of it." It doesn't.
Your IRA passes by the beneficiary form on file with your IRA company. If no one is named, the IRA's own default rules apply, and that is often your estate. An estate as beneficiary can mean a 5-year payout instead of 10 years or more for your heirs, plus time in probate.
Are the people I named still right?
Marriages, divorces, deaths and new grandchildren all change the answer. Check that every person named is still the one you want, that you have named backups ("contingent" beneficiaries), and that the shares add up the way you mean.
What if I name my estate or a charity?
Neither is a "designated beneficiary." If one is still on the form on September 30 of the year after your death, your IRA can be treated as having no designated beneficiary at all, even for the people you named next to it, unless the account is split or that share is paid out in time.
Should I name a trust?
Sometimes, for good reasons. A trust that meets four IRS tests lets the IRS look through it to the people who benefit. One that doesn't can shorten the payout. Have a tax or legal adviser review any trust you name.
What will my heirs face?
Most heirs other than a spouse must empty an inherited IRA within 10 years. If you die after your own required withdrawals have started, most must also take some out every year. The rules your heirs will follow.
Your free beneficiary review: what happens on the call?
A free 30-minute phone call with Rick Loek, RICP®.
Have the beneficiary forms for your IRAs and workplace plans in front of you. There is no need to send them. Rick walks through who is named, what each person faces under today's IRS rules, and what to ask your IRA company. It costs nothing, and there is nothing to buy or sign. Personal recommendations come only if you choose to become a client under a signed agreement.
Book my free beneficiary review (opens in a new window) Or call (279) 263-9218.To be open with you: Onesta is a fiduciary for the advice we give. Onesta is paid only by advisory fees. Rick is also a licensed insurance agent and may earn commissions on insurance or annuities through a separate company. Onesta does not sell insurance or annuities. You are never required to act on our advice. Rick is a member of Ed Slott's Master Elite IRA Advisor Group℠ (Master Elite since 2009). Membership does not imply endorsement by Ed Slott and Company.
The 5-step checklist for several beneficiaries
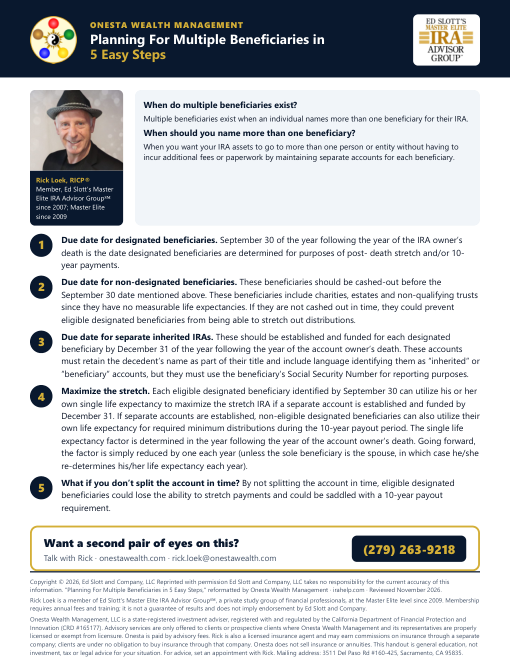
Free guide: Planning For Multiple Beneficiaries in 5 Easy Steps
For families sharing one IRA, and for owners naming more than one heir. Ed Slott's checklist, reprinted with permission.
A note on Step 4: yearly withdrawals inside the 10 years apply only if the owner died on or after their required beginning date. If the owner died before it, there are none, only the 10-year deadline. When they apply, the IRS uses the longer of the heir's life expectancy or the owner's remaining life expectancy.
Note by Onesta, checked against IRS rules, Reviewed November 2026. Ed Slott and Company did not write this note.
Copyright © 2026, Ed Slott and Company, LLC Reprinted with permission Ed Slott and Company, LLC takes no responsibility for the current accuracy of this information. "Planning For Multiple Beneficiaries in 5 Easy Steps," reformatted by Onesta Wealth Management · irahelp.com.
Want to read more before you check your forms? Start with this book.
-
The Little Book of Big Beneficiary Form Mistakes
By Ed Slott, with Ed Slott and Company's IRA experts
A short book of true stories. In each one, a single form on file sent money somewhere the owner never meant it to go. You can read it in an evening. Then pull out your own forms and see if they still say what you want.
See the book at Ed Slott and Company (opens in a new window)
-
Also on our reading list: The Forever Paycheck
By Jean Chatzky, 2026
A personal-finance journalist takes on the question most of us face when work stops: once the paychecks end, how do I pay myself each month? Read it as background. Talk with a professional before you act on any idea in it.

We suggest Ed's and Jean Chatzky's books as reading only. Onesta earns nothing if you buy them. Rick is a member of Ed Slott's Master Elite IRA Advisor Group℠ (Master Elite since 2009). Membership requires annual fees and training; it is not a guarantee of results and does not imply endorsement by Ed Slott and Company.
You may want to read Ed's book first or one of Rick's books (below): jump to Rick's books. Either way, you may want to have us review your beneficiary forms. No cost, and nothing to buy or sign.
Book a 30-minute call (opens in a new window) Or call (279) 263-9218.To be open with you: Onesta is a fiduciary for the advice we give. Onesta is paid only by advisory fees. Rick is also a licensed insurance agent and may earn commissions on insurance or annuities through a separate company. Onesta does not sell insurance or annuities. You are never required to act on our advice.
Questions people ask
Does my will decide who gets my IRA?
No. Your IRA passes by the beneficiary form on file with your IRA company.
What happens if I don't name an IRA beneficiary?
The IRA's own default rules apply, often naming your estate. An estate is not a designated beneficiary, which can mean a shorter payout for your heirs.
Can I name more than one beneficiary?
Yes. After your death the account can be split into a separate inherited IRA for each person, so each follows their own rules, if it is split by December 31 of the year after your death.
Is the call really complimentary?
Yes. The first conversation is complimentary, with no cost and no obligation. You are never required to act on our advice.
Keep reading
From the books by Rick Loek
Rick has written two books on money and retirement. They explain how he thinks about the bigger plan.
-
The Laws of Money
Unlock Wealth, Build Legacy, Transform Your Mindset · Richard Loek, 2024
#1 Best Seller in Business Education, Education Workbooks and Test Preparation, Amazon Kindle Store. Published December 2024.
Fourteen plain rules about money, one per chapter. Each chapter ends with questions to think about.
-
Retire with Confidence
Five Key Elements to Financial Freedom and Joy · Richard Loek and Mary Lee, 2024
#1 New Release in Retirement Planning, Taxation, and Studying & Workbooks, Amazon Kindle Store, August 2024.
The five things a retirement plan has to get right: income, risk, taxes, your estate and your investments.
See Retire with Confidence on Amazon (opens in a new tab)
Some chapters cover insurance or annuities. Onesta Wealth Management does not sell insurance or annuities. Onesta is paid only by advisory fees. Rick is also a licensed insurance agent. He may earn commissions on insurance or annuities through Calrima Senior Services and Insurance Solutions, Inc.


Want a second pair of eyes on your beneficiary forms?
Book a 30-minute call with Rick Loek, RICP®. Bring your questions about the IRA you inherited, or the one you will leave. Rick phones you at the time you pick. Your first conversation is complimentary, with no cost and no obligation.
Book a 30-minute call (opens in a new window)Or call (279) 263-9218 · rick.loek@onestawealth.com
To be open with you: Onesta is a fiduciary for the advice we give. Onesta is paid only by advisory fees. Rick is also a licensed insurance agent and may earn commissions on insurance or annuities through a separate company. Onesta does not sell insurance or annuities. You are never required to act on our advice.