Free guides
Free inherited IRA guides
Three one-page checklists. Free, with no sign-up and no email.
Reviewed November 2026 against IRS rules. Written by Onesta from IRS sources.
"Free means they want my email." Not here.
Each guide covers one situation in five steps. Pick the one that fits you.
They are Ed Slott's checklists, reprinted with permission. Ed's text is unchanged. Onesta changed the layout, colours, photo and contact details.
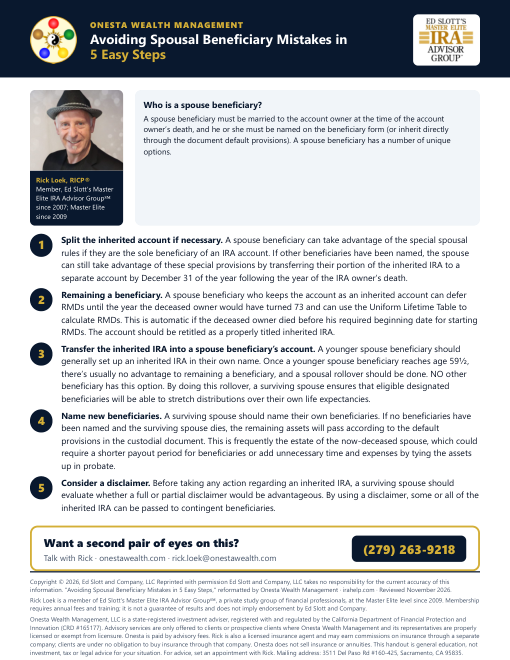
Free guide: Avoiding Spousal Beneficiary Mistakes in 5 Easy Steps
For a husband or wife who inherited their spouse's IRA. Ed Slott's checklist, reprinted with permission.
Before you use this guide: two points in Step 2 have changed. It says a spouse who keeps the account as a beneficiary can use the Uniform Lifetime Table. That comes from rules the IRS has proposed but not made final. Under the final rules, a spouse beneficiary uses the Single Life Table. It also says withdrawals can wait until the year your spouse would have turned 73. That wait applies only if your spouse died before their required beginning date, and the age is 75 if your spouse was born in 1960 or later. Ask your IRA company how it figures your required withdrawal.
Note by Onesta, checked against IRS rules, Reviewed November 2026. Ed Slott and Company did not write this note.
Copyright © 2026, Ed Slott and Company, LLC Reprinted with permission Ed Slott and Company, LLC takes no responsibility for the current accuracy of this information. "Avoiding Spousal Beneficiary Mistakes in 5 Easy Steps," reformatted by Onesta Wealth Management · irahelp.com.
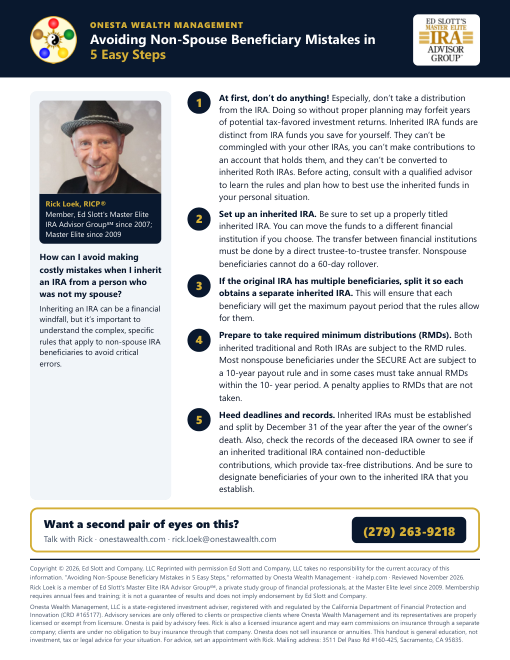
Free guide: Avoiding Non-Spouse Beneficiary Mistakes in 5 Easy Steps
For a child, grandchild, sibling or friend who inherited an IRA. Ed Slott's checklist, reprinted with permission.
A note on Step 5: December 31 of the year after death is the date to split the account so each heir uses their own schedule. You can split later, but the yearly amounts are then figured on the whole account. After-tax money in the IRA comes out partly tax-free, not wholly. IRS Form 8606 works out each part.
Note by Onesta, checked against IRS rules, Reviewed November 2026. Ed Slott and Company did not write this note.
Copyright © 2026, Ed Slott and Company, LLC Reprinted with permission Ed Slott and Company, LLC takes no responsibility for the current accuracy of this information. "Avoiding Non-Spouse Beneficiary Mistakes in 5 Easy Steps," reformatted by Onesta Wealth Management · irahelp.com.
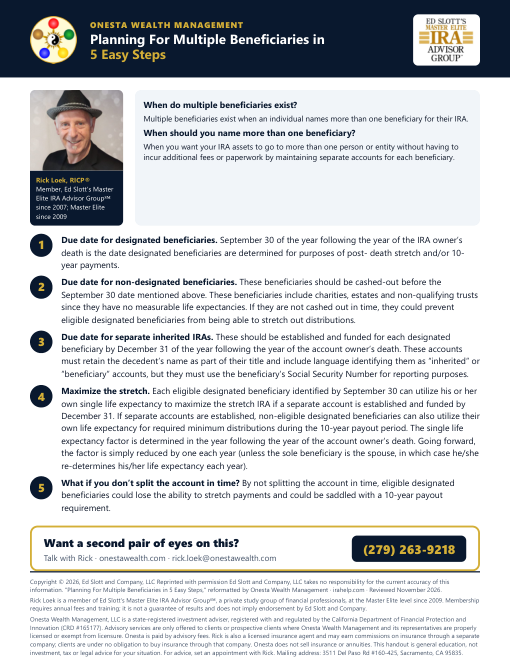
Free guide: Planning For Multiple Beneficiaries in 5 Easy Steps
For families sharing one IRA, and for owners naming more than one heir. Ed Slott's checklist, reprinted with permission.
A note on Step 4: yearly withdrawals inside the 10 years apply only if the owner died on or after their required beginning date. If the owner died before it, there are none, only the 10-year deadline. When they apply, the IRS uses the longer of the heir's life expectancy or the owner's remaining life expectancy.
Note by Onesta, checked against IRS rules, Reviewed November 2026. Ed Slott and Company did not write this note.
Copyright © 2026, Ed Slott and Company, LLC Reprinted with permission Ed Slott and Company, LLC takes no responsibility for the current accuracy of this information. "Planning For Multiple Beneficiaries in 5 Easy Steps," reformatted by Onesta Wealth Management · irahelp.com.
Want the stories behind these checklists? We recommend Ed Slott's book on beneficiary form mistakes. See our reading pick.
Is anything in them out of date?
A few points have changed. The IRS made its rules final in 2024. Some points are still only proposed.
Where a guide differs from the final rules, a note from Onesta sits above its download button. Our pages follow the final rules: the spouse page, the non-spouse page and the multiple-beneficiaries page.
Questions people ask
Are the guides really free?
Yes. No sign-up. No email. Pick a guide and it opens.
Who wrote the guides?
Ed Slott and Company wrote them. Onesta reprinted them with permission. Ed's text is unchanged. We changed the layout, colours, photo and contact details.
Why is there an Onesta note above the guide link?
Ed Slott's one-page guides stay word for word as approved. The IRS made its rules final in 2024, though a few points remain proposed. When a guide says something older, Onesta puts a dated note above the button. Those notes cover the spouse table, age 75 for owners born in 1960 or later, the year-end split date, Form 8606 basis, and yearly payouts.
Keep reading
From the books by Rick Loek
Rick has written two books on money and retirement. They explain how he thinks about the bigger plan.
-
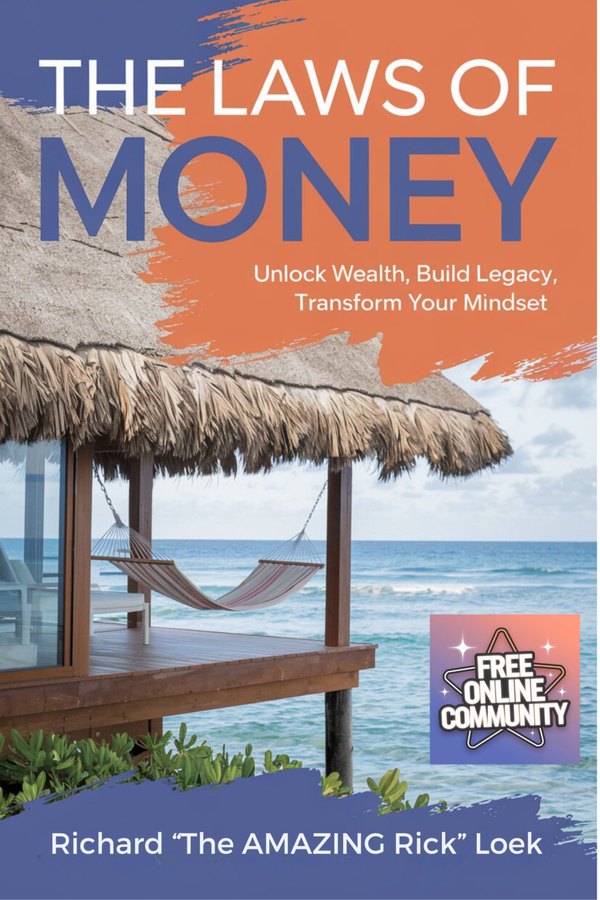
The Laws of Money
Unlock Wealth, Build Legacy, Transform Your Mindset · Richard Loek, 2024
#1 Best Seller in Business Education, Education Workbooks and Test Preparation, Amazon Kindle Store. Published December 2024.
Fourteen plain rules about money, one per chapter. Each chapter ends with questions to think about.
-
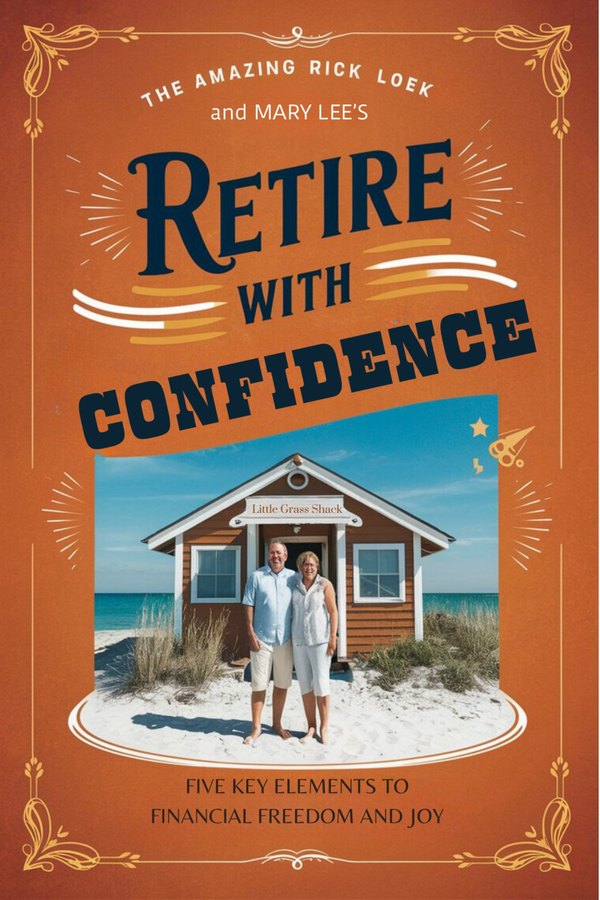
Retire with Confidence
Five Key Elements to Financial Freedom and Joy · Richard Loek and Mary Lee, 2024
#1 New Release in Retirement Planning, Taxation, and Studying & Workbooks, Amazon Kindle Store, August 2024.
The five things a retirement plan has to get right: income, risk, taxes, your estate and your investments.
See Retire with Confidence on Amazon (opens in a new tab)
Some chapters cover insurance or annuities. Onesta Wealth Management does not sell insurance or annuities. Onesta is paid only by advisory fees. Rick is also a licensed insurance agent. He may earn commissions on insurance or annuities through Calrima Senior Services and Insurance Solutions, Inc.


Want a second pair of eyes on this?
Book a 30-minute call with Rick Loek, RICP®. Bring your questions about the IRA you inherited, or the one you will leave. Rick phones you at the time you pick. Your first conversation is complimentary, with no cost and no obligation.
Book a 30-minute call (opens in a new window)Or call (279) 263-9218 · rick.loek@onestawealth.com
To be open with you: Onesta is a fiduciary for the advice we give. Onesta is paid only by advisory fees. Rick is also a licensed insurance agent and may earn commissions on insurance or annuities through a separate company. Onesta does not sell insurance or annuities. You are never required to act on our advice.